Investment services in and around Walled Lake
State Farm Can Help With Your Financial Aspirations
State Farm offers a variety of financial services products, including mutual funds, annuities and variable universal life.
Retirement and IRAs
The IRA options that State Farm offers - Traditional or Roth - both allow your earnings to grow tax deferred. There are other advantages specific to each, though, that your Walled Lake, MI State Farm agent Katie Jones can help you understand.
Investment Services
Are you looking to establish an emergency fund, invest for retirement, or plan for college expenses? State Farm agents are ready to help you know where to begin.
Education Savings Plans
When saving for college, anyone can contribute.
Estate Planning
It can get confusing to try to think through all the goals and options you may have. That's why including State Farm agent Katie Jones can be a worthwhile resource. Your agent can help educate you on your choices regarding insurance that may be right for you and your beneficiaries.
Annuities
Depending on when you want your income payout to begin, your stage of life, your goals, and other factors, there are different options available for the type of annuity that may help you reach your goals. Your local registered agent Katie Jones can help you as you explore the specifics.
Business Retirement Plans
Quality employees can make a large difference in a small business. A significant way to attract and retain employees is to offer the benefit of a retirement plan.
You Have Financial Aspirations. Let Us Help!

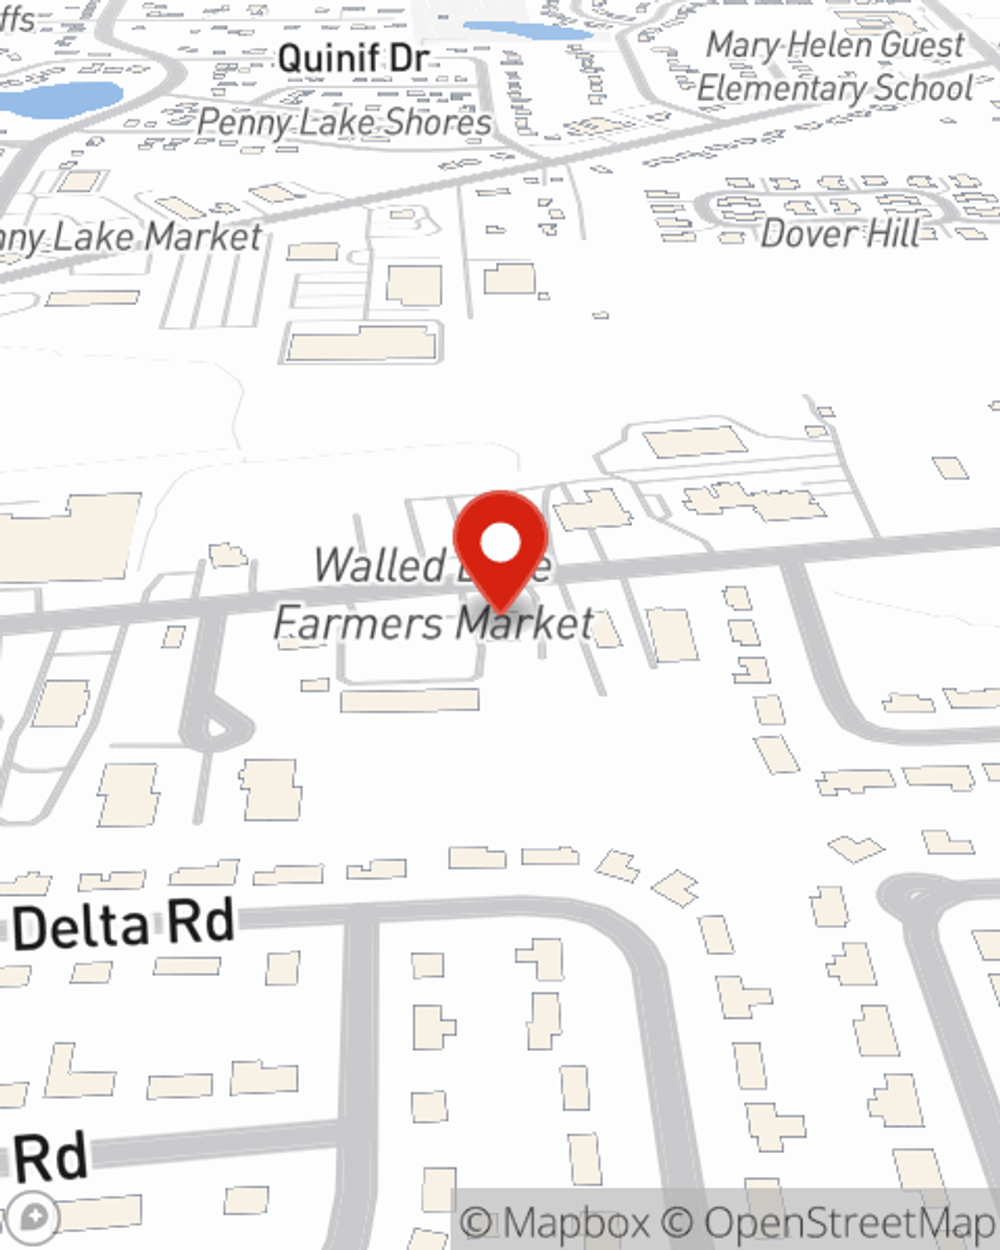
A great choice for help reaching financial goals in the Walled Lake area
Let's work toward your financial dreams
Simple Insights®
How to use the 50/30/20 budget rule
How to use the 50/30/20 budget rule
Balance your personal spending and saving with the 50/30/20 budget rule. Discover how much should be used for everyday needs, wants and savings.
When should you start spending retirement savings?
When should you start spending retirement savings?
The age to start withdrawing from retirement accounts varies from person to person. What guidelines can you use to know when to start spending?